Checking the grounds
The amount of debt, the length of delay, the property you own and any transactions in recent years. Based on this we say plainly whether the procedure suits you or not.
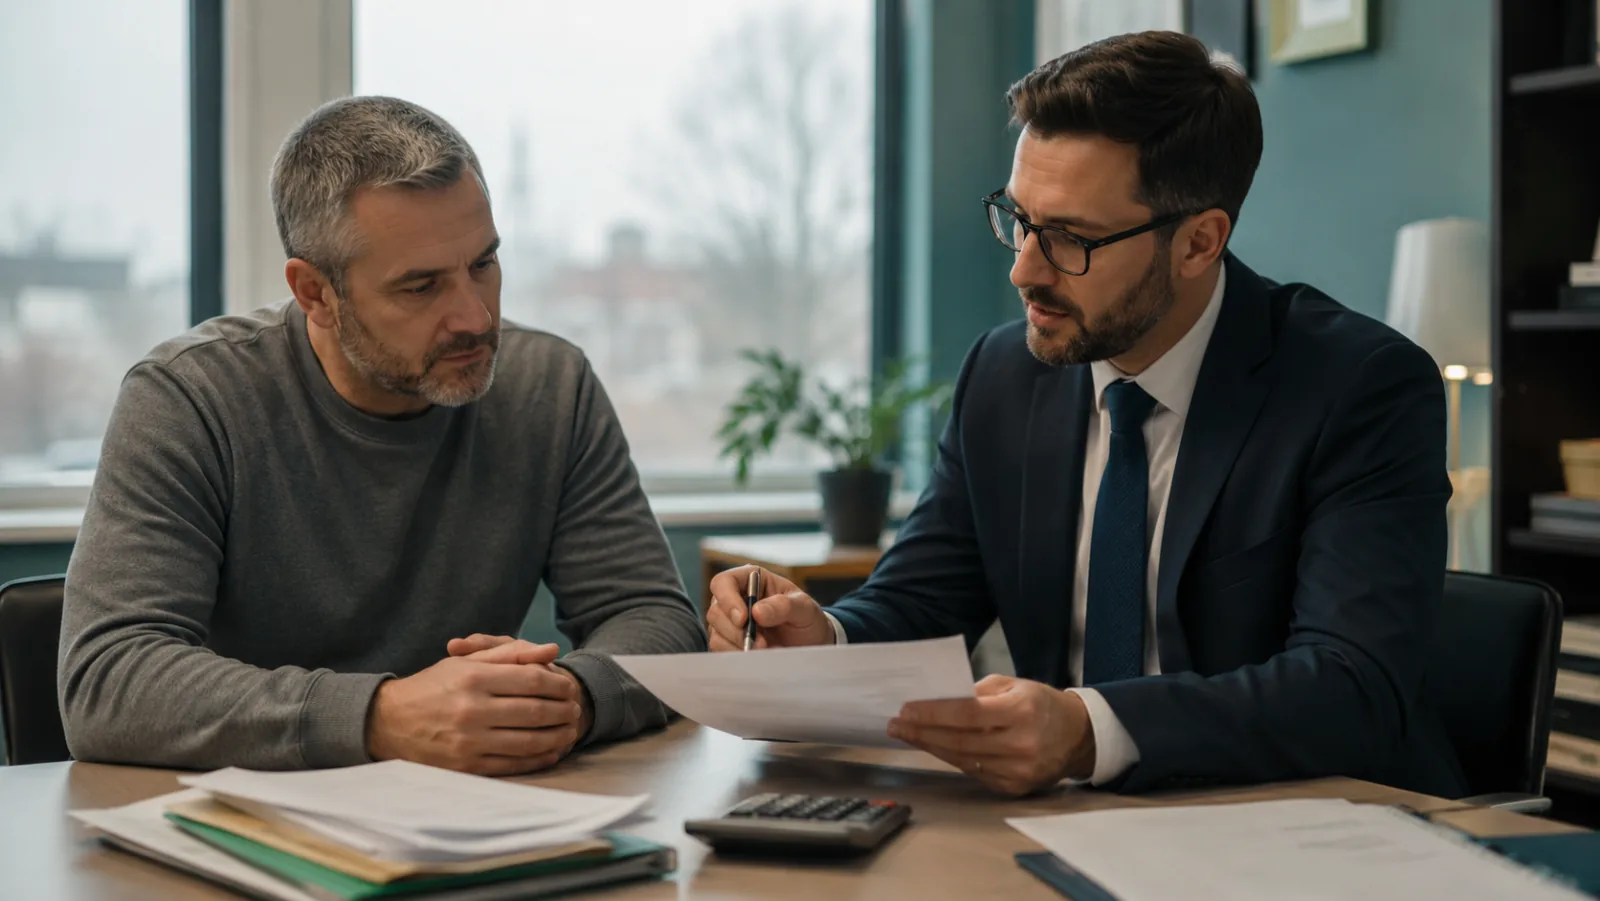
We check compliance with the conditions before filing the application
We support the out-of-court procedure and court bankruptcy
We prepare documents and work with the financial administrator
We protect property that cannot be subject to enforcement
We see the case through to debt write-off and supporting documents
Tell us about your debts and property — we will tell you honestly whether bankruptcy suits you or whether another route is cheaper.
Message us on WhatsAppThe amount of debt, the length of delay, the property you own and any transactions in recent years. Based on this we say plainly whether the procedure suits you or not.
Out-of-court is simpler and cheaper, but has strict conditions. Court bankruptcy is more accessible by criteria, but takes longer and involves a trustee.
A full set: list of creditors, inventory of property, statements of income and transactions. Mistakes here mean the application is returned.
Notifications, objections to inflated claims, checking the calculations of banks and debt collectors included in the register.
We support the entire dialogue: requests, reports, creditors' meetings. The client does not have to work out the procedure on their own.
The only home and essential items are not sold. We make sure nothing unnecessary ends up in the bankruptcy estate.
We examine transactions from previous years: the sale or gifting of property to relatives is almost always challenged by the administrator.
The ruling on completion of the procedure, discharge of debt, certificates for banks and removal of restrictions.
A third of those who approach us leave without a procedure: in some cases restructuring is cheaper, in others the debt can simply be recalculated. We will tell you this straight away.
Cost
Indicative prices. The exact amount is quoted after the grounds have been checked and depends on the number of creditors and the presence of property.
| Service | What is included | Cost |
|---|---|---|
| Check of grounds | Analysis of debts, property and transactions, conclusion on the procedure | free of charge |
| Legal opinion | A written analysis with a calculation of costs and consequences | from 30,000 ₸ |
| Out-of-court procedure | Preparation and filing of the application, support | from 150,000 ₸ |
| Court bankruptcy on a turnkey basis | Full support until the debt is discharged | from 250,000 ₸ |
| Complex procedure | Several creditors, property, challenging transactions | from 400,000 ₸ |
| Objections to a creditor's claim | Reviewing the calculation and excluding inflated amounts | from 50,000 ₸ |
| Protection of property in the procedure | Excluding property from the bankruptcy estate | from 70,000 ₸ |
| Support after completion | Certificates, lifting restrictions, working with databases | from 35,000 ₸ |
The prices are given for reference and do not constitute a public offer. The state fee, the financial administrator's remuneration, publications and postal expenses are paid separately.
We calculate debts, review income, property and transactions over the preceding years.
Whether you formally qualify and whether it is worthwhile. Sometimes the answer is "do not start", and that is an honest answer.
Certificates of debt, statements, documents for property, information on income and family composition.
We prepare the package so that it is not returned: the list of creditors and the inventory of property are the most common grounds for refusal.
Requests, reports, register of claims. We handle correspondence and participate in creditors' meetings.
We check the calculations of banks and debt collectors: inflated claims are excluded from the register.
If there is any — we control the valuation and the sale procedure, we protect what is not subject to sale.
We obtain the ruling on completion and documents confirming release from obligations.
Tell us the amount of debt and the composition of your property — we will calculate what you will get and what you will lose.
Team
We handle a case from start to finish with the same team: you always know who is dealing with your matter and who to contact.
Lawyer for civil cases
Handles disputes over real estate, inheritance, contracts and transactions. Supports transactions from document review through to registration of title.
Lawyer for financial and motor vehicle disputes
Works with banks, insurers and debt collectors, handles recovery and bankruptcy cases, and defends drivers in administrative matters.
Lawyer for family and social matters
Handles divorces, division of property, alimony and disputes over children, as well as employment, pension and social issues.
Lawyer for corporate law
Supports company transactions, arranges shares and corporate agreements, handles disputes between participants and reorganisation.
Tax lawyer
Challenges notifications and inspection reports, handles tax disputes in court, supports inspections and recovers overpayments.
Construction and contract lawyer
Reviews contract agreements, estimates and acts, handles disputes over quality and scope of works, supports acceptance of facilities.
Intellectual property and IT lawyer
Protects copyright and trademarks, drafts contracts for IT teams and handles rights to products and code.
Bankruptcy and debt recovery lawyer
Handles bankruptcy and rehabilitation procedures, recovers receivables, defends directors against subsidiary liability.
Practice
Details have been changed and anonymised: the content of the case is protected by professional privilege.
Useful information
A person comes in with the same thought: the debts are bigger than he could ever repay. Debt collectors call his relatives, the bank has gone to court, enforcement proceedings drag on for years, and part of his income goes to deductions. In such a situation it is easy to make one of two mistakes — to keep paying in circles for years, hoping to settle up, or, on the contrary, to rush into the first procedure that comes along without checking whether it fits.
A mistake is also costly because bankruptcy is not the only way out, nor a universal one. Sometimes it is more advantageous to recalculate the debt, agree on instalments, or challenge excessive interest and penalties. And sometimes the procedure really is started, but poorly prepared — with spoiled documents, assets moved out, transactions that are later set aside. Let us go through it in order: where bankruptcy is appropriate, and where a person will only lose time and money.
Personal bankruptcy is not a universal cure for debts. In our experience, roughly one in three people who come to us does not need the procedure: the obligations can be closed through restructuring, a deferral, or a recalculation of penalties and interest. At the first consultation, a lawyer for personal bankruptcy assesses whether there is any point in going to court, or whether it is more sensible to agree a change of payment schedule with the creditor.
The procedure is justified when the debt clearly exceeds the value of the property, the defaults have lasted a long time, and the income does not even cover the interest. A good lawyer for personal bankruptcy first looks at what the debt consists of: sometimes part of the penalties and commissions can be challenged or written off without going to court. If the creditors have already gone to court, court enforcement officers are at work, and the property is under threat — bankruptcy becomes a real way out. A legal consultation on bankruptcy helps you understand which path suits you specifically.
The procedure is established by the Law of the Republic of Kazakhstan on Restoration of Solvency and Bankruptcy of Citizens of the Republic of Kazakhstan. The procedure is established by the Law of the Republic of Kazakhstan on Restoration of Solvency and Bankruptcy of Citizens of the Republic of Kazakhstan. The procedure is established by the Law of the Republic of Kazakhstan on Restoration of Solvency and Bankruptcy of Citizens of the Republic of Kazakhstan. The procedure is established by the Law of the Republic of Kazakhstan on Restoration of Solvency and Bankruptcy of Citizens of the Republic of Kazakhstan. Out-of-court bankruptcy of an individual suits those who have no property to settle with creditors and no disputes: the debt is recognised as hopeless, and the bankruptcy procedure for a citizen goes through the authorised body and takes several months. Judicial bankruptcy is already a court hearing, where transactions, property and the debtor's good faith are examined; it usually lasts from six months to a year, and drags on longer where there is property and disputes with creditors.
Personal bankruptcy cases are taken through the court where transactions need to be challenged or property realised. The out-of-court track is not suitable for that. Separately, the law provides for restoration of solvency: a debtor with a regular income keeps his property and settles with creditors under a plan approved by the court. Separately, the law provides for restoration of solvency: a debtor with a regular income keeps his property and settles with creditors under a plan approved by the court. Separately, the law provides for restoration of solvency: a debtor with a regular income keeps his property and settles with creditors under a plan approved by the court. Separately, the law provides for restoration of solvency: a debtor with a regular income keeps his property and settles with creditors under a plan approved by the court. An online consultation with a bankruptcy lawyer helps you understand in advance which path applies in your particular situation and which documents will be needed.
Payment for personal bankruptcy services does not come down to a single figure for filing an application. When people compare how much a lawyer for personal bankruptcy costs, the calculation takes in the whole scope of work: from the initial analysis of debts and a bankruptcy consultation to supporting the procedure through to completion. The price of personal bankruptcy is made up of the preparation of documents and the number of creditors that will have to be dealt with.
The cost of a turnkey bankruptcy depends on how tangled the situation with property, transactions and income is, whether there are disputes with court enforcement officers and objections from creditors. The price of personal bankruptcy also includes work with the financial manager, participation in court hearings, and preparation of the inventory of property. Firms dealing with personal bankruptcy calculate this workload differently, but the set of stages is usually the same:
The presence of property does not remove the possibility of bankruptcy itself, but it changes the course of the case. Bankruptcy without property is simpler: the absence of property is confirmed by the court enforcement officer — the enforcement document is returned to the claimant, and creditors cannot count on repayment through sale. Bankruptcy with preservation of property requires more delicate work: the law protects some items from realisation, the rest are inventoried, valued and put up for auction, and the dispute over what exactly falls into the estate is decided in court. That is why, before filing an application, it is important to understand what property the debtor has and what will happen to it.
The only home, as a rule, cannot be taken away — it is not subject to realisation. The exception is a flat under mortgage: it is the subject of a pledge, and this requires separate analysis. In other cases, the debtor should collect in advance the documents confirming the status of the home so that it is not included in the estate.
The discharge of debts is not unlimited. Alimony, compensation for harm to life and health, and claims arising from intentional infliction of damage remain with the person even after the procedure is completed. These obligations are tied to personal rights and intentional actions, so the law does not allow release from them.
Everything else, where the conduct is in good faith, is written off. Legal assistance in bankruptcy is needed in order to assess the composition of the debts correctly and not lose the chance of discharge. If the case shows signs of bad faith, creditors raise objections, and then a legal consultation on personal bankruptcy helps to build a defence. Firms dealing with personal bankruptcy and individual lawyers in Almaty start precisely with an analysis of the obligations: what will be written off and what will remain.
If the debtor transferred an apartment, a car or a share in a business to relatives before filing the application, this will almost always come to light. The administrator reviews transactions from previous years and challenges those concluded in the run-up to bankruptcy. The property is returned to the estate, and the discharge from debts may be refused.
Deliberate bankruptcy of an individual is not only the risk of losing transferred property. Challenging a transaction means creditors will be satisfied out of the returned assets, and the debtor will lose the discharge. That is why, before starting the procedure, it is worth honestly assessing one's actions and getting bankruptcy advice in order to understand which transactions will be reviewed first. Bankruptcy of individuals — a lawyer's help is also needed to properly build a defence in respect of transactions already made and not to harm oneself with new ones.
The start of the procedure changes the balance of power: from that moment creditors file their claims only within the bankruptcy case, and separate enforcement proceedings are suspended. Debt collectors lose any reason to call and write to the debtor directly — their claims move into the common register. In practice this means the phone stops ringing off the hook, and the pressure on the debtor and their family fades away.
If the calls continue after the documents are filed, this is no longer debt collection but a breach of procedure — such facts are recorded: a recording of the conversation, correspondence, the date and number of the call. These materials are added to the case, and the persistence of the debt collectors turns against them. Legal services for bankruptcy include this work too: handling correspondence with creditors, monitoring suspended enforcement proceedings with a private or state court enforcement officer. Bankruptcy of individuals with the help of a lawyer relieves a person of the need to explain themselves to every caller. Below is what exactly stops automatically:
Calls and messages from debt collectors and banks stop.
Enforcement proceedings on old debts are suspended.
Creditors' claims are considered only through the bankruptcy procedure.
New claims and deductions on these debts do not proceed outside the case.
Turnkey bankruptcy means that all correspondence with banks, microfinance organisations, debt collectors and the financial administrator is handled by lawyers and advocates. The client only needs to collect the documents and sign the prepared papers. If you are looking for an advocate for the bankruptcy of individuals, it is important to understand: a bankruptcy advocate and a bankruptcy lawyer work together, so the services of a bankruptcy advocate are not limited to court hearings.
Turnkey bankruptcy of individuals removes the need to personally answer calls and letters from creditors: the advocate handles communication with them. This approach saves time and reduces the risk of mistakes in correspondence. Below are the tasks the specialist covers.
Bankruptcy of individuals and legal entities are two different legal institutions with dissimilar objectives. A citizen goes through the procedure as a consumer: the court reviews transactions, income and good faith, and the outcome is a discharge from obligations. A company is made bankrupt in order to settle with creditors out of its property; the managers do not get a personal discharge of debts.
The choice of route depends on who owes. An insolvent citizen needs a lawyer for the bankruptcy of individuals: he runs the case, prepares the application, and supports the challenging of transactions. When the problem concerns a company, lawyers for the bankruptcy of legal entities are required: protection from creditors, assessment of the risks of subsidiary liability. Bankruptcy of legal entities and of citizens is united only by the goal — to stop the growth of debt. Before starting, consultations on bankruptcy are essential:
Formally, it is possible to go through bankruptcy with no property and without the help of a specialist: the law does not require a lawyer to be involved, and a citizen is entitled to collect the documents and file the application themselves. In practice, everything comes down to the details. Applications are returned when the list of creditors is incomplete or the inventory of property is drawn up inaccurately, and the court requires confirmation of every fact.
Errors in transactions over recent years are the most common reason for refusing to write off debts: an incorrect assessment of a transaction, a missed deadline for challenging it, the absence of supporting documents. That is why, before filing, it is worth finding a lawyer for personal bankruptcy and going through your situation: a good lawyer for personal bankruptcy sees the risk of refusal before the court does, and a bankruptcy lawyer in Almaty knows how local courts assess inventories and transactions.
At the start of the procedure, a package of documents is assembled: identity card, IIN, certificates of income and pension contributions, statements on accounts and loan agreements, information on property and transactions over recent years, details of family and place of registration. If the person worked or had the status of an individual entrepreneur, tax reporting and documents on obligations will be needed, including enforcement proceedings with a private or state court enforcement officer.
The support then covers the entire course of the case: analysis of the debt, preparation of the application, correspondence with banks and the administrator, protection of interests in court and monitoring of enforcement. Legal services for personal bankruptcy are built around the client receiving an analysis of their situation and a clear plan, rather than general promises. Over the years of practice, more than 90 procedures have been handled — both out-of-court and court bankruptcy.
| Stage | Task | Who handles it |
|---|---|---|
| Preparation | Analysis of debts and collection of documents | Client and lawyer |
| Application | Preparation and filing | Lawyer |
| Dealing with creditors | Banks, debt collectors, trustee | Lawyer |
| Court | Defending the position | Lawyer and advocate |
| Completion | Monitoring compliance | Lawyer |
The volume of documents depends on the composition of debts and the presence of property.
Once the personal bankruptcy procedure is completed, legal consequences follow that are important to consider in advance. For several years, when applying for credit, a person must disclose that they have undergone bankruptcy. This does not affect employment, but the law restricts access to new loans for several years and prohibits undergoing the procedure again.
To understand which consequences of personal bankruptcy will affect you specifically, you need a consultation with a personal bankruptcy lawyer. A legal consultation on personal bankruptcy helps assess the risks, examine your debt situation and choose between the procedure and the other options mentioned above. Consultations on personal bankruptcy are held before the case begins: the earlier you examine your circumstances, the fewer mistakes and losses there will be. During the consultation it also becomes clear what the procedure offers and what to expect after it is completed.
| Consequence | What it involves | What it affects |
|---|---|---|
| Notification of bankruptcy | When applying for credit, the procedure must be disclosed | Banks and creditors |
| Repeat bankruptcy | A new procedure can only be started after the period established by law has expired | Possibility of repeat discharge |
| Employment | Generally not restricted | Hiring |
| Term | Several years | Duration of consequences |
The consequences last for several years; their scope depends on the specific situation and the completion of the case.
First check whether the procedure suits you and what will happen to your property, and only then decide whether to start it. Rushing and trying to hide assets harm the debtor more than the debt itself.
Reviews
Four loans and two microloans, I stopped paying back in 2024, because after being made redundant at work I simply didn't have the strength to keep pulling all of it. I looked for a lawyer because I was afraid of getting lost in the paperwork myself and missing something important. We went through the court procedure in ten months, the debt was written off, it was morally hard, but they did everything on the documents for me
Service: Lawyer for personal bankruptcy in Almaty
Serik, thank you for the review. We're glad we could take you through the procedure and lift that burden off you. If any questions come up about the documents after completion, do get in touch.
I had accumulated debts on loans, and I didn't know what to do anymore, the banks called every day. I found this company through a friend, she said they explain things properly here. I came, talked to Dmitry, he asked everything about my situation. Honestly, I was sure they'd tell me to do bankruptcy, since that's their job after all. But he looked at the documents and said it would be better for me to first try recalculation with restructuring, because I have a stable income. I was even surprised, usually it's the other way around and they drag you into an expensive procedure.
Service: Lawyer for personal bankruptcy in Almaty
I came with debts I was already tired of thinking about, and wanted to understand what could be done at all. There had been a sale of a car to my brother a year before filing, the lawyer warned me straight away that it would be challenged, and that's exactly what happened. Good thing I knew in advance and didn't build up any illusions, though sometimes I had to wait for an answer and bring in a couple of documents myself
Service: Lawyer for personal bankruptcy in Almaty
I came with several debts and had no idea where to start. The out-of-court procedure went smoothly, Yerlan explained everything to me step by step in detail. The main thing was to collect the documents correctly, they were accepted first time
Service: Lawyer for personal bankruptcy in Almaty
I ran into the fact that a collector filed a claim with interest twice as much as under the contract. At first I was at a loss, I didn't understand how that was even possible or where to complain. I came to them, showed the contract and the correspondence, and they explained that this could be worked with. Objections were filed, the excess was removed from the register. I waited several weeks for the result, was a bit nervous, but they did everything without me. What I particularly appreciated was that they explained things in plain words rather than throwing terms around. In the end the amount became reasonable, not the one the collectors had calculated
Service: Lawyer for personal bankruptcy in Almaty
The debts had been piling up for years, and I no longer saw a way out, that's why I went to a lawyer. What I feared most was losing the flat, it's my only one. They explained it wouldn't be touched, and that's how it turned out. The calls stopped right after the procedure began. Before that I used to flinch at every unknown number. Here, for the first time in a long while, I could sleep peacefully. Everything went step by step, they kept me informed. Thank you for not leaving me alone with this
Service: Lawyer for personal bankruptcy in Almaty
The situation was tough, four loans and two microloans, I'd had nothing to pay with for a year already. I came to them because I was already confused myself and didn't know what to grab hold of. Madina laid it all out for me, explained which documents were needed and what to expect. We went through the procedure, the debts were written off. The main thing is the calls stopped right away, even before the end. Before, I was afraid to pick up even from my relatives. Here I finally breathed out. Thank you for your patience and for answering my questions a hundred times
Service: Lawyer for personal bankruptcy in Almaty
I was afraid they'd take the flat, that was the scariest thing for me. Sanzhar calmly explained that your only home is preserved. That's how it turned out, everything went without shocks
Service: Lawyer for personal bankruptcy in Almaty
Oksana, thank you for your trust. We're glad we could dispel your fears and handle the case calmly. If you need anything, we're in touch.
We spent a long time collecting documents, I kept forgetting something. They didn't rush me, they reminded me. We made it to the end.
Service: Lawyer for personal bankruptcy in Almaty
Мен банкроттық туралы көп ойландым, бірақ қайдан бастауды білмедім, сондықтан кеңес сұрап бардым. Маған честно айтты, менің жағдайым соттан тыс рәсімге келмейді, сот арқылы өтуге тура келеді. Жеңіл жол уәде етпеді, бұл маған ұнады. Нәтижесінде бәрі сәтті болды, бірақ күткеннен де ұзақ уақыт алды. Шыдамдылық керек екен, бірақ нәтижесіне ризамын
Service: Lawyer for personal bankruptcy in Almaty
The debts were written off, I still can't believe it's legal and could have been done for free earlier. True, a couple of times I had to wait for an answer and bring in documents, but that's small stuff. Thank you very much
Service: Lawyer for personal bankruptcy in Almaty
I came with debts and a constant fear of calls from the banks, I no longer knew where to turn. The most valuable thing was that they took over communication with the banks entirely, Yerlan handled everything himself. I stopped being afraid of phone calls
Service: Lawyer for personal bankruptcy in Almaty
Tatyana, thank you for your kind words. We are glad we could take that worry off your shoulders. If any questions come up, please get in touch.
There was a car deal a year before filing, I thought it did not matter and would not even have remembered it. The lawyer immediately asked about deals over the past three years. Good thing he asked, otherwise I would have been refused
Service: Lawyer for personal bankruptcy in Almaty
Almas, thank you for sharing. Such details really are important to check in advance so as not to lose time on a refusal. We are glad everything worked out.
Everything went through, without unnecessary fuss or surprises. Thank you for your work
Service: Lawyer for personal bankruptcy in Almaty
Vera, thank you for the review. We are glad the procedure went smoothly. Get in touch if you need anything.
The procedure took about eight months. At the start they warned me it would not be quick, and so it was. The specialist handling it kept telling me when and which documents were needed. The wait was long, but it went without surprises. I am happy with the result, now I sleep peacefully
Service: Lawyer for personal bankruptcy in Almaty
I came with credit card debt of about three million. First we tried to agree a restructuring with the bank, it did not work out. Then we went into the procedure. They explained everything at every step.
Service: Lawyer for personal bankruptcy in Almaty
Good specialists, no fluff, straight to the point. Asel explained everything quickly and did not overload me with unnecessary stuff. I would come back again
Service: Lawyer for personal bankruptcy in Almaty
I came with debts, some of them were alimony, I thought everything would be written off. They told me honestly that part of the alimony debt would not be written off under any circumstances. I was upset, but it is better to know straight away than later. Then we discussed what could really be done with the rest. Everything went according to plan, they did not abandon me, they answered my questions. Although the alimony left a bitter aftertaste, at least there were no illusions. The rest was written off, and that is already a big relief. Thank you for not promising the impossible
Service: Lawyer for personal bankruptcy in Almaty
I came with debts and wanted to understand what actually suited me, because I had heard little about bankruptcy. They helped me go through the out-of-court procedure, it turned out to be faster and cheaper. They checked that I qualified for it, before that I did not even know such an option existed
Service: Lawyer for personal bankruptcy in Almaty
I came to them when I had completely given up, there were a lot of debts and it was embarrassing to even talk about it. They worked correctly and without judgment, that was important to me. The situation is unpleasant, but the attitude was normal and human. Nobody looked down on me, everything was calmly explained. Though sometimes I waited several days for an answer, but that's minor. Big thanks to them.
Service: Lawyer for personal bankruptcy in Almaty
Galina, thank you for your warm words. We understand how hard it is to take such a step, and we are glad you felt comfortable with us. If you need help, please get in touch.
Blog
Conditions of the out-of-court procedure and the consequences that are rarely mentioned.
Read the analysis
What to look at in the statement and which charges the court most often removes.
Read the analysis
When a debtor enters bankruptcy proceedings, ordinary enforcement stops: money can only be obtained through the register of creditors' claims.
Read the analysis
What restrictions apply after the procedure and what remains with the debtor.
Read the analysis
Restrictions on calls and conversations with relatives, and where to complain.
Read the analysis
When reaching an agreement is more beneficial than going through the procedure to the end.
Read the analysisFAQ
As a rule, no: the only home is not subject to sale. The exception is a flat under a mortgage, it is the subject of pledge, and this requires a separate review.
Alimony, compensation for harm to life and health, claims arising from intentional infliction of damage. Other obligations are discharged if the conduct is in good faith.
The out-of-court one — several months. The judicial one — usually from six months to a year, longer if there is property and disputes with creditors.
Formally, yes. In practice, applications are returned because of an incomplete list of creditors and an inventory of property, and errors in transactions lead to a refusal to discharge the debts.
The administrator will check transactions from previous years and challenge them. The property will be returned to the bankruptcy estate, and discharge from debts may be refused.
Yes, once the procedure begins, claims are submitted only through it, and enforcement proceedings are suspended.
For several years you must disclose the bankruptcy when obtaining credit, and there are restrictions on certain positions. It does not generally affect employment.
In addition to the lawyer's fee — the administrator's remuneration, the state fee and publications. We give the full estimate at a free consultation, before filing the application.
The assessment of the grounds is free. The cost of support depends on the procedure — the out-of-court one is cheaper than the court one — and on the number of creditors. The administrator's remuneration, publications and fees are paid separately, and we warn about them before the contract.
Yes. We assess your situation in numbers and tell you straight: whether you qualify for the procedure or whether it is cheaper to restructure the debt. Roughly every third person does not need bankruptcy.
Yes, that is what turnkey work means: we handle the correspondence with creditors, collection agencies and the financial administrator. You provide the documents and your signature.
Contacts and maps
2GIS opens in a separate tab — the service does not allow embedding an organisation card.
Open in 2GISZoon opens in a separate tab: client reviews and ratings are there.
Open on ZoonThe first consultation is free. If the matter can be resolved without court, we will say so directly.