Underpayment
The most common case: the insurer's calculation is based on inflated wear and tear and an understated hourly rate. The difference is recovered through a pre-action claim or court.
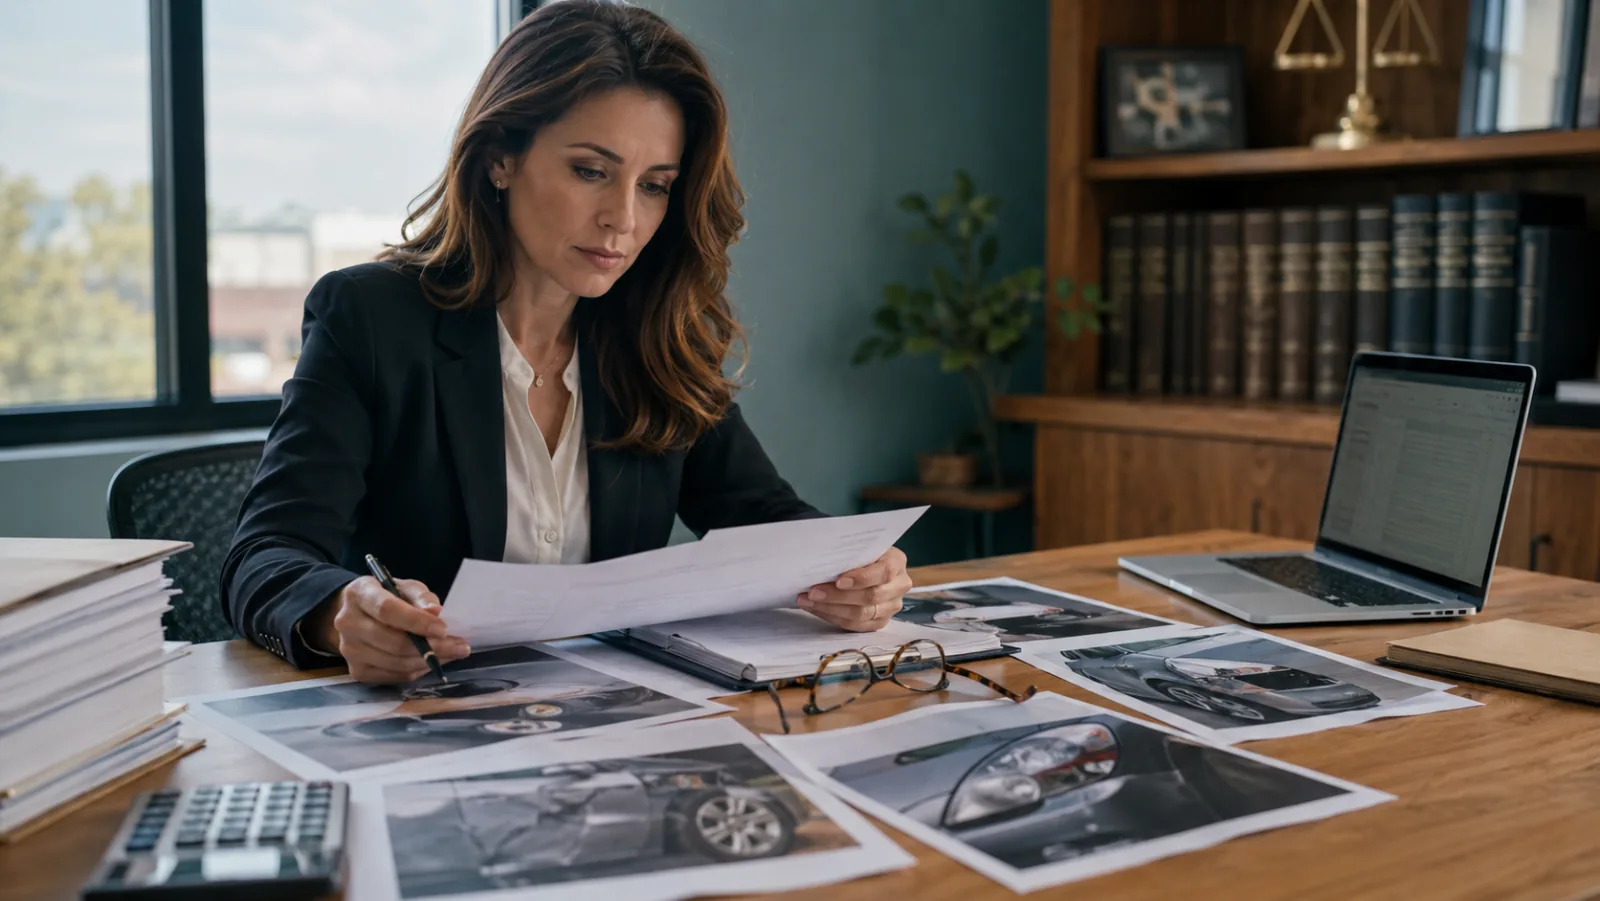
We handle disputes under compulsory civil liability insurance, CASCO, home and health insurance
We challenge refusals and understated calculations by insurance companies
We calculate the penalty for each day of delayed payment
We work with independent assessment and forensic examination
We see the case through until the money actually reaches the account
Send us the insurer's calculation or refusal — we will tell you how much was underpaid and whether it is worth disputing.
Message us on WhatsAppThe most common case: the insurer's calculation is based on inflated wear and tear and an understated hourly rate. The difference is recovered through a pre-action claim or court.
A refusal without reference to a specific clause of the rules, references to 'unforeseen circumstances' and late notification — all of these can be challenged.
The insurer drags things out and keeps asking for documents in circles. A penalty accrues for each day of delay, which the company itself will not remind you about.
If fault is determined incorrectly, there will be no payment at all. We challenge this through case materials, camera footage and motor vehicle technical expertise.
Refusal due to a deductible, the 'wrong' driver behind the wheel or the absence of an alarm system. We examine the contract and the insurance rules in full.
Flooding, fire, theft: understatement of the repair sum, refusal on formal grounds, dispute over wear and tear of finishes.
Denials for injuries and illnesses, disputes over the amount of insurance cover, recovery upon the occurrence of an insured event.
We handle the case without your involvement and see the recovery through until the money reaches your account.
The first consultation is free. If the underpayment is less than the cost of the dispute, we will say so directly and advise you on how to act on your own.
Cost
Indicative prices. The exact amount is quoted after reviewing the insurance contract and the insurer's calculation.
| Service | What is included | Cost |
|---|---|---|
| Consultation on a denial or calculation | Review of the insurer's documents and assessment of the prospects | free of charge |
| Legal opinion | A written review of the contract, insurance rules and calculation | from 25,000 ₸ |
| Claim to the insurance company | Calculation of the underpayment and penalty, sending of the claim | from 30,000 ₸ |
| Statement of claim against the insurance company | Drafting the claim with a calculation of the demands and annexes | from 45,000 ₸ |
| Conduct of an insurance dispute in court | Full support of first-instance proceedings through to judgment | from 160,000 ₸ |
| Dispute over the party at fault in a road traffic accident | Work with case materials and forensic motor-vehicle examination | from 180,000 ₸ |
| Appeal | Challenging a judgment where the amount awarded by the court is too low | from 70,000 ₸ |
| Enforcement proceedings | Recovery of the amount awarded until the money is received | from 60,000 ₸ |
Prices are for reference only and do not constitute a public offer. An independent valuation, forensic examination and state duty are paid separately and directly to the provider.
The grounds for refusal almost always lie in the insurance rules, not in the law. We start with them.
We look at wear and tear, the hourly rate, the list of parts. This is where the underpayment shows up.
We arrange an inspection and a calculation of the real cost of repairs. This is the key document in the dispute.
A penalty for each day of delay is added to the underpayment. It is often comparable to the additional payment itself.
We send a demand with the calculation. Some companies pay the difference without going to court.
We prepare the claim, attend court under a power of attorney, and if necessary — a forensic examination.
If the court reduced the amount or disregarded the assessment, we go to appeal.
We support enforcement proceedings until the funds reach your account.
Send us the calculation or the refusal — we will work out how much should have been paid and prepare a claim.
Team
We handle a case from start to finish with the same team: you always know who is dealing with your matter and who to contact.
Lawyer for civil cases
Handles disputes over real estate, inheritance, contracts and transactions. Supports transactions from document review through to registration of title.
Lawyer for financial and motor vehicle disputes
Works with banks, insurers and debt collectors, handles recovery and bankruptcy cases, and defends drivers in administrative matters.
Lawyer for family and social matters
Handles divorces, division of property, alimony and disputes over children, as well as employment, pension and social issues.
Lawyer for corporate law
Supports company transactions, arranges shares and corporate agreements, handles disputes between participants and reorganisation.
Tax lawyer
Challenges notifications and inspection reports, handles tax disputes in court, supports inspections and recovers overpayments.
Construction and contract lawyer
Reviews contract agreements, estimates and acts, handles disputes over quality and scope of works, supports acceptance of facilities.
Intellectual property and IT lawyer
Protects copyright and trademarks, drafts contracts for IT teams and handles rights to products and code.
Bankruptcy and debt recovery lawyer
Handles bankruptcy and rehabilitation procedures, recovers receivables, defends directors against subsidiary liability.
Practice
Details have been changed and anonymised: the content of the case is protected by professional privilege.
Useful information
Most often the dispute with an insurer is not about whether the event occurred but about the figure: you assess the damage by actual expenses, the insurer by its own methodology, and the difference can be several times over. Then the correspondence begins, in which a person without preparation wastes time and signs what should not have been signed. The mistakes of the first days — agreeing to the amount, the absence of an independent assessment, oral agreements — are expensive to fix later.
Situations vary: a refusal under comprehensive insurance after a road accident, undervaluation under compulsory third-party liability insurance, a dispute over a life and health payment, a flooded flat, or a refusal of social benefits. Each case has its own procedure, its own set of evidence and its own authority to complain to. Below are the practical forks in the road: what to calculate, what to prove it with, in what order to proceed, and when court can no longer be avoided.
The payment was undervalued, refused, or the insurer is stalling — that is already a dispute. An insurance disputes lawyer checks whether the rules were applied lawfully and secures a recalculation or payment. Undervaluation is an incorrect assessment of damage, a refusal is a formal ground, a delay is "additional checks".
An insurance claims lawyer works not only with motor vehicles but also with policies for housing, property, life and health. The earlier an insurance lawyer is brought in, the fewer mistakes there are — from carrying out repairs independently to agreeing to a "favourable" top-up. The dispute is then resolved depending on the type of policy:
| The situation as presented by the insurer | What it looks like in practice | What is disputed |
|---|---|---|
| Understated payment | Damage assessed incompletely | Calculation, wear and tear, scope of work |
| Refusal | Reference to a formal ground | Grounds for refusal, whether the event occurred |
| Delay | Checks with no result | Right to payment and interest |
| Top-up "on the spot" | Condition — sign the consent | Terms of the settlement agreement |
Each situation is a reason to check the documents and the calculation before signing any consents.
Compulsory civil liability insurance of vehicle owners and voluntary CASCO operate under different rules, and a dispute with the company is built differently in each case. In the first, the payment goes to the injured party for the harm caused by the driver, while in the second it goes to the owner for damage to their own car, so neither the parties involved, nor the list of grounds for refusal, nor the way the amount of damage is calculated are the same.
To understand which type your situation falls under, look at the policy and at who received the payment. This is where the difference in tactics shows: an insurance law lawyer identifies a separate set of documents, a separate line of objections and a separate appeals procedure for each type of dispute. A mistake at the outset — for example, assessing damage using the methodology for a different policy — usually leads to a refusal that is then hard to overturn. An insurance lawyer in Almaty starts precisely with checking the policy and the insurance rules for your type.
An understated payment is almost always based on the insurance company's internal assessment. Its calculation may rely on an incomplete inspection, outdated parts price guides or an understated wear-and-tear percentage. Until there is an alternative calculation, the dispute is about one side's figures, and the court or the ombudsman simply has nothing to compare the positions against. That is precisely why an independent assessment of damage becomes the main argument in a dispute over the amount.
Such an assessment must be carried out by a qualified assessor who is a member of the chamber of assessors and has confirmed qualifications. The report calculating the market value of restorative repair or the value of lost property must be attached to the claim before filing a complaint or a lawsuit. If the insurer refuses to accept the report, this is recorded in writing and subsequently strengthens the position of the insured. A lawyer practising insurance law works precisely on the basis of such evidence, and an insurance lawyer in Almaty checks whether the report meets the requirements set by the insurer and the court.
The insurance company is obliged to issue a refusal in writing and stating the grounds. It is this document that opens the dispute: until there is a written refusal, there is nothing to discuss. If the insurer refers to an 'incomplete package' or a 'non-insured event', these wordings become the starting point for the claim.
A claim is built not on emotions but on an analysis of the grounds for refusal. The task is to show that each argument of the insurer does not correspond to the terms of the contract, the insurance rules or the circumstances of the case. An insurance company lawyer in such disputes usually relies on interpreting the rules in their own favour, so the claim must close off these arguments one by one: confirm the event, the status of the insured, the amount of damage and the absence of lawful grounds for refusal. A lawyer in an insurance company sees the weak points of their position in advance, and a well-drafted claim often forces a reconsideration of the decision before trial.
A dispute with an insurer begins not with court but with a written claim to the company itself: without it, the ombudsman and the court will not take up the matter. After that, the route depends on the substance of the dispute. If the amount is contested — an underpayment under CASCO, compulsory third-party liability or a life payout — the path lies through the insurance ombudsman or the court. If the refusal itself is contested, especially on a clearly contrived ground, the court usually seeks not a recalculation but a declaration that the refusal is unlawful and an order to pay.
A separate track is a complaint to the regulator of the insurance market: it does not award payment, but it records the violation and influences the company. This is where legal assistance with insurance companies is needed: lawyers for insurance cases and insurance lawyers prepare the claim, the complaint and the lawsuit so that the arguments do not fall apart on formalities.
Personal insurance — life, health, accident — is structured differently from motor or property insurance. The insurer does not argue about the market price of repair: it checks whether the event was insured and whether the information was fully disclosed when the contract was concluded. Most often the refusal is justified by the client not having reported illnesses, sports, bad habits or past visits to a doctor. This is where an insurance lawyer is needed, to build the defence around medical documents rather than general words.
The key is to prove a causal link between the event and the consequence: diagnosis, hospitalisation, expert examination, discharge summaries, results of examinations. If the insurer refers to incomplete disclosure, it is important to show that it itself did not ask questions or received truthful answers. A practising lawyer for insurance disputes checks whether the grounds for refusal correspond to the contract and the insurance rules, and prepares a claim or a lawsuit based on the collected medical evidence.
An insurance payout and a state benefit are different things, and they must not be confused. Insurance money is paid by a private company under a contract: compulsory third-party liability insurance, CASCO, life insurance, property insurance. Benefits, on the other hand, are awarded by the state on social grounds — for loss of a breadwinner, disability, or caring for a child.
And a dispute over a benefit is built on different documents: income statements, certificates of family composition, medical reports, the decision of the authorised body refusing or understating the payment. But the logic of support is similar: a benefits lawyer gathers evidence, prepares an application to a higher body, challenges the refusal in court and secures a recalculation. The mistakes are usually the same: the appeal deadline has been missed, there is no written refusal, the calculation was made on incorrect income data.
When an insurer pays compensation, it is important to understand the limits of its liability: part of the damage can only be claimed from the person who caused it. In practice, insurance lawyers split claims between two targets, because this determines to whom the claim is made and in what amount.
Under compulsory third-party liability insurance, the insurer is liable within the established compensation, and anything not covered by the payout remains the debt of the person at fault. The difference between the payout and the actual damage can be recovered from the person at fault if there are supporting documents.
| Claim | From the insurer | From the person at fault | Basis |
|---|---|---|---|
| Insurance compensation | Within the limit | No | Compulsory third-party liability insurance or CASCO |
| Excess over the actual damage | No | Yes | Discrepancy in documents |
| Valuation costs | Depends on the type | Yes, if not covered | Confirmation of expenses |
| Moral damage in property matters | No | Limited | Tort claim |
A lawyer handling an insurance dispute takes into account the type of contract and the actual documents: under CASCO, claims against the person who caused the harm have their own specifics.
Disputes over home and property insurance most often concern the assessment of damage, the causes of the event and the interpretation of exclusions in the contract. The insurer may insist that the reported event does not fall under the policy terms, or may factor in wear and tear when calculating the payout. If the flat is insured and the compensation does not cover the actual repairs or the value of the lost property, it is worth showing the documents to a lawyer specialising in insurance law.
Mistakes in such cases are costly: the owner agrees to the first valuation offered, fails to record the damage before repairs, or misses the deadlines for appeal. A lawyer specialising in insurance law helps gather evidence, challenge an undervaluation and prepare a claim or a statement of claim. What is checked first:
A complaint to the Agency for Regulation and Development of the Financial Market works as leverage when the insurer delays payment, stays silent in response to a claim or replies with a formal brush-off. The regulator does not award money and does not replace the court, but its enquiry changes the company's behaviour: an inspection, a request for documents and a demand to explain its position often speed up a resolution faster than correspondence with a branch. A lawyer for insurance disputes files such an application not instead of a claim, but alongside it, so that the party has both a supervisory and a judicial line of pressure.
It is important to understand the limits: the regulator examines breaches of rules and licensing requirements, not the amount of damage itself. If the dispute is about the sum, the supervisory route alone will not return the money, but it can expose a systemic practice of undervaluation. For the client this is an additional argument in negotiations and in court, and sometimes a reason for the company to reconsider its position before the hearing. What is worth bearing in mind before filing a complaint:
The application is filed on the official website or in writing, with copies of the claim and the insurer's replies.
Record the dates: when you submitted the documents, when you received a refusal or silence.
Attach the valuer's report if you are challenging the sum — without it the regulator will see only the correspondence.
State that you have already sent a claim and are awaiting a response; a complaint without the pre-trial step is weaker.
In parallel, prepare the statement of claim: deadlines in a dispute do not wait, and the supervisory track moves at its own pace.
If the insurer underpaid, refused or is dragging out the decision, bring a full set of papers to the consultation with a lawyer in insurance disputes. The fewer the documents, the more cautiously the claims are formulated: with only a calculation, the dispute is about the additional payment; with the correspondence with the insurer, it is about delay and penalty. Without the insurance rules it is impossible to understand what exactly the company breached and what you are entitled to claim.
A lawyer in insurance cases also looks at the correspondence: letters, responses to the claim, notices of extension of deadlines. A missed letter often decides whether there was a delay. Bring the insurer's assessment report together with the independent valuer's report as well.
Collect:
The deadlines in an insurance dispute depend on the type of claim and the moment when you learned of the breach. For property disputes the deadlines are general, for payments connected with life and health they are extended, and for social benefits the deadlines are special. That is precisely why in Almaty an insurance lawyer first determines the date from which the deadline started to run, and only then builds the position. If the deadline is missed, it can be restored only for valid reasons, otherwise the court will return the claim and the road to court will be closed.
The enforcement of the court decision is ensured by the court enforcement officer: under a contract with the claimant — a private one, for certain categories and for claims against state bodies — a state one. After the decision enters into force, the lawyer or advocate in insurance disputes needs to obtain the writ of execution and hand it to the court enforcement officer together with an application. The enforcement officer then searches for accounts and property and withholds the amounts, while you monitor how the proceedings are progressing. Mistakes at these two stages cost the most: a missed deadline or an incorrect enforcement document.
What matters in practice:
The main mistake is to agree with the amount or the refusal without obtaining the insurer's written reasoning and without recording the damage independently: it is precisely these two documents that decide the dispute in court.
Reviews
The insurer paid 310 thousand, the valuation showed 890. We sent a pre-action claim, and they paid the shortfall without court in three weeks.
Service: Insurance disputes lawyer in Almaty
They refused, saying it wasn't an insured event, and that was that. Dmitry sat down and calmly went through the rules — it turned out there was no such ground there at all. We won in court and even recovered a penalty; I didn't believe it until the very end.
Service: Insurance disputes lawyer in Almaty
Kasko, the car was damaged in a parking lot, the culprit's license plate wasn't found. The insurance company dragged it out for four months, they responded slowly, I already started calling myself. Then the lawyers calculated the penalty and everything moved. I had to bring a few papers that I hadn't brought right away, but that's minor. In the end I got more than I expected. Thank you
Service: Insurance disputes lawyer in Almaty
The flat was flooded, the insurer calculated pennies for the decoration — I was upset to the point of tears. Yerlan helped gather the documents and challenge their calculation; they added almost three times as much. It took a while, but there's a result.
Service: Insurance disputes lawyer in Almaty
There was a road accident, according to the report I turned out to be at fault, but I didn't agree with it. Because I wasn't at fault, and there were witnesses. So I looked for a lawyer, I thought if I kept arguing myself it would just take time. The expert examination confirmed what I said, my version turned out to be correct. In the end I got the payment, I waited a long time but I don't regret it
Service: Insurance disputes lawyer in Almaty
Thank you, Nurlan! In a disputed matter the expert examination was of great importance, we're glad about the result. If you need help, get in touch.
I came with the refusal already in hand — the insurer claimed I had notified them of the event too late. They told me honestly that the prospects were slim because of the missed deadline, but they tried anyway. They recovered part of it, and I appreciate that they didn't promise more than they could.
Service: Insurance disputes lawyer in Almaty
The insurer underpaid three times less after the accident, I repaired the car at my own expense. I came to the lawyers already in despair, because I didn't understand how to prove the real cost of the repair myself. They did an independent valuation, and it put everything in its place. It turned out their calculation was, to put it mildly, understated. They paid the shortfall even before court, I didn't even expect such a turn. The communication was calm, they explained everything in plain language. I waited a bit for the valuation results, but it was worth it. I got the money, the car is repaired. Thank you
Service: Insurance disputes lawyer in Almaty
After the accident the insurer refused me with reference to a clause in the rules that no one had shown me when I took out the policy. I was in shock, because I had paid regularly and thought everything was insured. I went to the lawyers, because I didn't understand where to look for that clause or how to read it. It turned out the wording in the contract was completely different, and that clause had nothing to do with my case at all. They calmly went through the whole contract and explained where the insurer had overstepped. They prepared objections and challenged the refusal. I waited a long time for a response from the insurer, I had to remind them a couple of times. In the end I got the payment, although at first it seemed the case was hopeless. Thank you for your patience and clear explanations
Service: Insurance disputes lawyer in Almaty
Thank you for the detailed review! We're glad we got to the bottom of the contract and secured the payment. If any questions come up, get in touch.
the flat was flooded from above, the neighbours wouldn't admit fault. the insurer dragged it out for three months, Asel helped gather the documents and file them properly. they recovered both the payment and a penalty for the delay
Service: Insurance disputes lawyer in Almaty
CASCO, refusal allegedly for breaching the conditions of keeping the car — I was baffled. We proved that the condition in the contract was worded differently from how they interpret it.
Service: Insurance disputes lawyer in Almaty
Thank you for the review! Indeed, the wording in a contract is often interpreted by the insurer not in the client's favour. We're glad we managed to restore justice.
I repaid the loan early and didn't understand whether part of the insurance would be returned. I couldn't get anywhere with the bank myself, they just shrugged. I came to the lawyers, they helped recover part of the insurance on early repayment of the loan.
Service: Insurance disputes lawyer in Almaty
Thank you for the review! Early repayment is a common situation where part of the insurance can be recovered. Get in touch if you need help.
They calculated the wear and tear at the maximum and listed the parts as repairable. The expert examination showed the opposite.
Service: Insurance disputes lawyer in Almaty
Everything was clear. They explained that you must not sign a settlement agreement before the assessment.
Service: Insurance disputes lawyer in Almaty
The medical insurance didn't cover the treatment, even though it should have under the contract. I ended up in hospital, and the insurer started making excuses that the case wasn't covered. I had no strength or time to fight on my own, I was still recovering at the time. A friend recommended lawyers who handle insurance disputes. I came in with a pile of papers, didn't even believe anything would come of it. They laid it all out, gathered the missing certificates. The correspondence with the insurer dragged on, I was already tired of waiting. But in the end they sorted it out and the treatment was paid for. Very grateful that they didn't leave me alone in that situation.
Service: Insurance disputes lawyer in Almaty
Thank you for the kind words! Health is the most important thing, and we're glad we managed to get the treatment paid for. Get well soon!
After the road accident the insurer offered a sum that wasn't even enough for part of the repairs. I didn't know where to turn, because I don't understand damage assessment myself. They helped recalculate, and in the end the sum almost doubled compared to what was offered.
Service: Insurance disputes lawyer in Almaty
The insurer delayed the payment by several months, I just waited and didn't know anything could be done. Sanzhar pointed out that a penalty is due for the delay, and they recovered it separately. I didn't even know about it, that's the story
Service: Insurance disputes lawyer in Almaty
Thank you for sharing! The penalty for delay is an important part of protecting a client's rights, and we're glad we helped recover it.
The cargo was damaged in transit, and the carrier refused to admit fault. I went to the insurer, but there they started looking for reasons to refuse. I'm not a lawyer myself, so I went to those who handle such cases. At first it wasn't clear who was even supposed to pay. I had to bring in several more documents on the cargo, I hadn't gathered everything at once. The lawyers got in touch with the carrier and the insurer, then the case went to court. I waited for answers longer than I expected, that was a bit stressful. But in the end the damage was compensated through the insurer and the court. Thanks for the work, though it took quite a toll on my nerves
Service: Insurance disputes lawyer in Almaty
There was a fire in the house, we were left with almost nothing, and the insurer calculated pennies. I came in a panic, didn't know how to go on. Dmitry helped recalculate through an independent assessment, the sum grew several times over.
Service: Insurance disputes lawyer in Almaty
I had a long dispute with the insurance company, this case dragged on for eight months. They didn't want to acknowledge my claims, kept giving different excuses each time. The lawyers sorted out all the documents and took it to court. The wait was long, honestly I got tired. But in the end we recovered everything we asked for, I'm satisfied with the result
Service: Insurance disputes lawyer in Almaty
After the car accident they refused me verbally, they didn't give a written refusal, I don't know why they did that. I came to the lawyers because without a paper you can't go anywhere. Erlan helped me draft the application and forced them to issue a written refusal. After that it went easier, I could already work with the document. thanks for the help
Service: Insurance disputes lawyer in Almaty
Blog
An independent assessment, a claim and the deadlines you must not miss.
Read the analysis
What to film at the scene and which wordings work against you.
Read the analysis
Procedural violations that most often save your driving licence.
Read the analysis
The assessor's report, the calculation and a reasonable deadline for a reply.
Read the analysis
What to do if the rules were never given to you when the contract was concluded.
Read the analysis
When the limit is not enough and how the remaining damage is calculated.
Read the analysisFAQ
It depends on the difference between the insurer's calculation and the actual cost of repairs. In our cases the payout most often increases by one and a half to three times, plus a penalty for late payment.
Almost always. Without it, a dispute over the amount has nothing to rest on. Its cost, as a rule, is recovered from the insurer together with the underpayment.
It is harder, but not always hopeless: it can be challenged if the agreement was signed under a misapprehension or hidden damage was discovered later. The text needs to be looked at.
Record the dates of submitting documents and demand written replies. A penalty accrues for late payment, and it must be claimed as a separate demand.
The pre-trial stage is two to four weeks. With court it is usually two to four months to a decision, plus enforcement proceedings.
It is challenged through the materials of the administrative case, camera recordings and an auto-technical expert examination. This is a separate dispute, and the very possibility of a payout depends on it.
Yes. Under CASCO the disputes are more often about exclusions, the deductible and the driver permitted to drive — here it is important to read the insurance rules in full.
We will say so honestly. Sometimes the cost of a lawyer and an expert examination eats up the benefit, and it is more sensible to act on your own — we will tell you how.
The consultation is free. A claim to the insurer and handling the case are charged separately. An independent assessment is paid for separately, but its cost, as a rule, is recovered from the insurer.
Yes. Send the policy, the insurance rules and the insurer's calculation as photos — from them you can immediately see which clause was seized upon in the refusal.
Yes. Flooding and fire in a home, life and health insurance, insurance taken out with a loan, cargo and carrier liability, medical insurance.
Contacts and maps
2GIS opens in a separate tab — the service does not allow embedding an organisation card.
Open in 2GISZoon opens in a separate tab: client reviews and ratings are there.
Open on ZoonThe first consultation is free. If the matter can be resolved without court, we will say so directly.